IC Markets

 3:09
 2:39
 2:10
 2:18
 3:43
 8:42

Hong Kong’s Forex Volume Hit a Record: Why It Matters to You
Hong Kong FX turnover hit record levels, making it Asia's largest forex centre with Singapore and Tokyo. What that means for spreads and liquidity.
 WriterAbir KhanWriterWrites the guides · checks every figure against primary sources View profileAbout Abir →

 Market analysisTanbir Habib RiyadForex & Crypto AnalystForex and crypto analyst · technical and fundamental analysis View profileAbout Tanbir →

 Fact-checking & riskJannatul FerdaushFact-Checker & Risk AnalystFact-checks every figure · risk analysis · Applied Statistics, University of Dhaka View profileAbout Jannatul →

 Trading reviewJowel RanaForex TraderForex trader · reviews guides from a trader's view View profileAbout Jowel →

 Final approvalRanjan N. MondolForex TraderForex trader · signs off every guide View profileAbout Ranjan →

Key takeaways
- Hong Kong's FX turnover hit a record $883.1 billion a day in April 2025, up 27% from 2022 (HKMA, BIS survey).
- That makes it the world's fourth-largest FX centre, driven largely by the offshore yuan (CNH).
- More banks quoting in Asian hours has tightened spreads on CNH and regional pairs.
- The growth is China-linked, so USD/CNH liquidity is still policy-sensitive and thins around China events.
Every three years the Bank for International Settlements surveys global foreign exchange turnover, and the between-survey data from national regulators fills in the picture. Hong Kong’s reported FX turnover hit a record $883.1 billion a day in April 2025, according to the Hong Kong Monetary Authority's release of the 2025 BIS Triennial Survey, up 27% from 2022 and enough to make it the fourth-largest forex centre in the world, behind Singapore in Asia. For a retail trader in the region, that growth has practical effects worth understanding.
Why Hong Kong is a big FX centre
- It is the main offshore hub for the Chinese yuan (CNH), and CNH trading has grown as China’s economy and the yuan’s international use have expanded.
- It sits in the Asian time zone, so it captures flow during Asian hours that would otherwise be thinner.
- It has a deep concentration of international banks, deregulated markets, and a legal system that global institutions are comfortable with.
- It benefits from proximity to mainland Chinese demand for hedging and cross-border trade settlement.
What the growth means for you
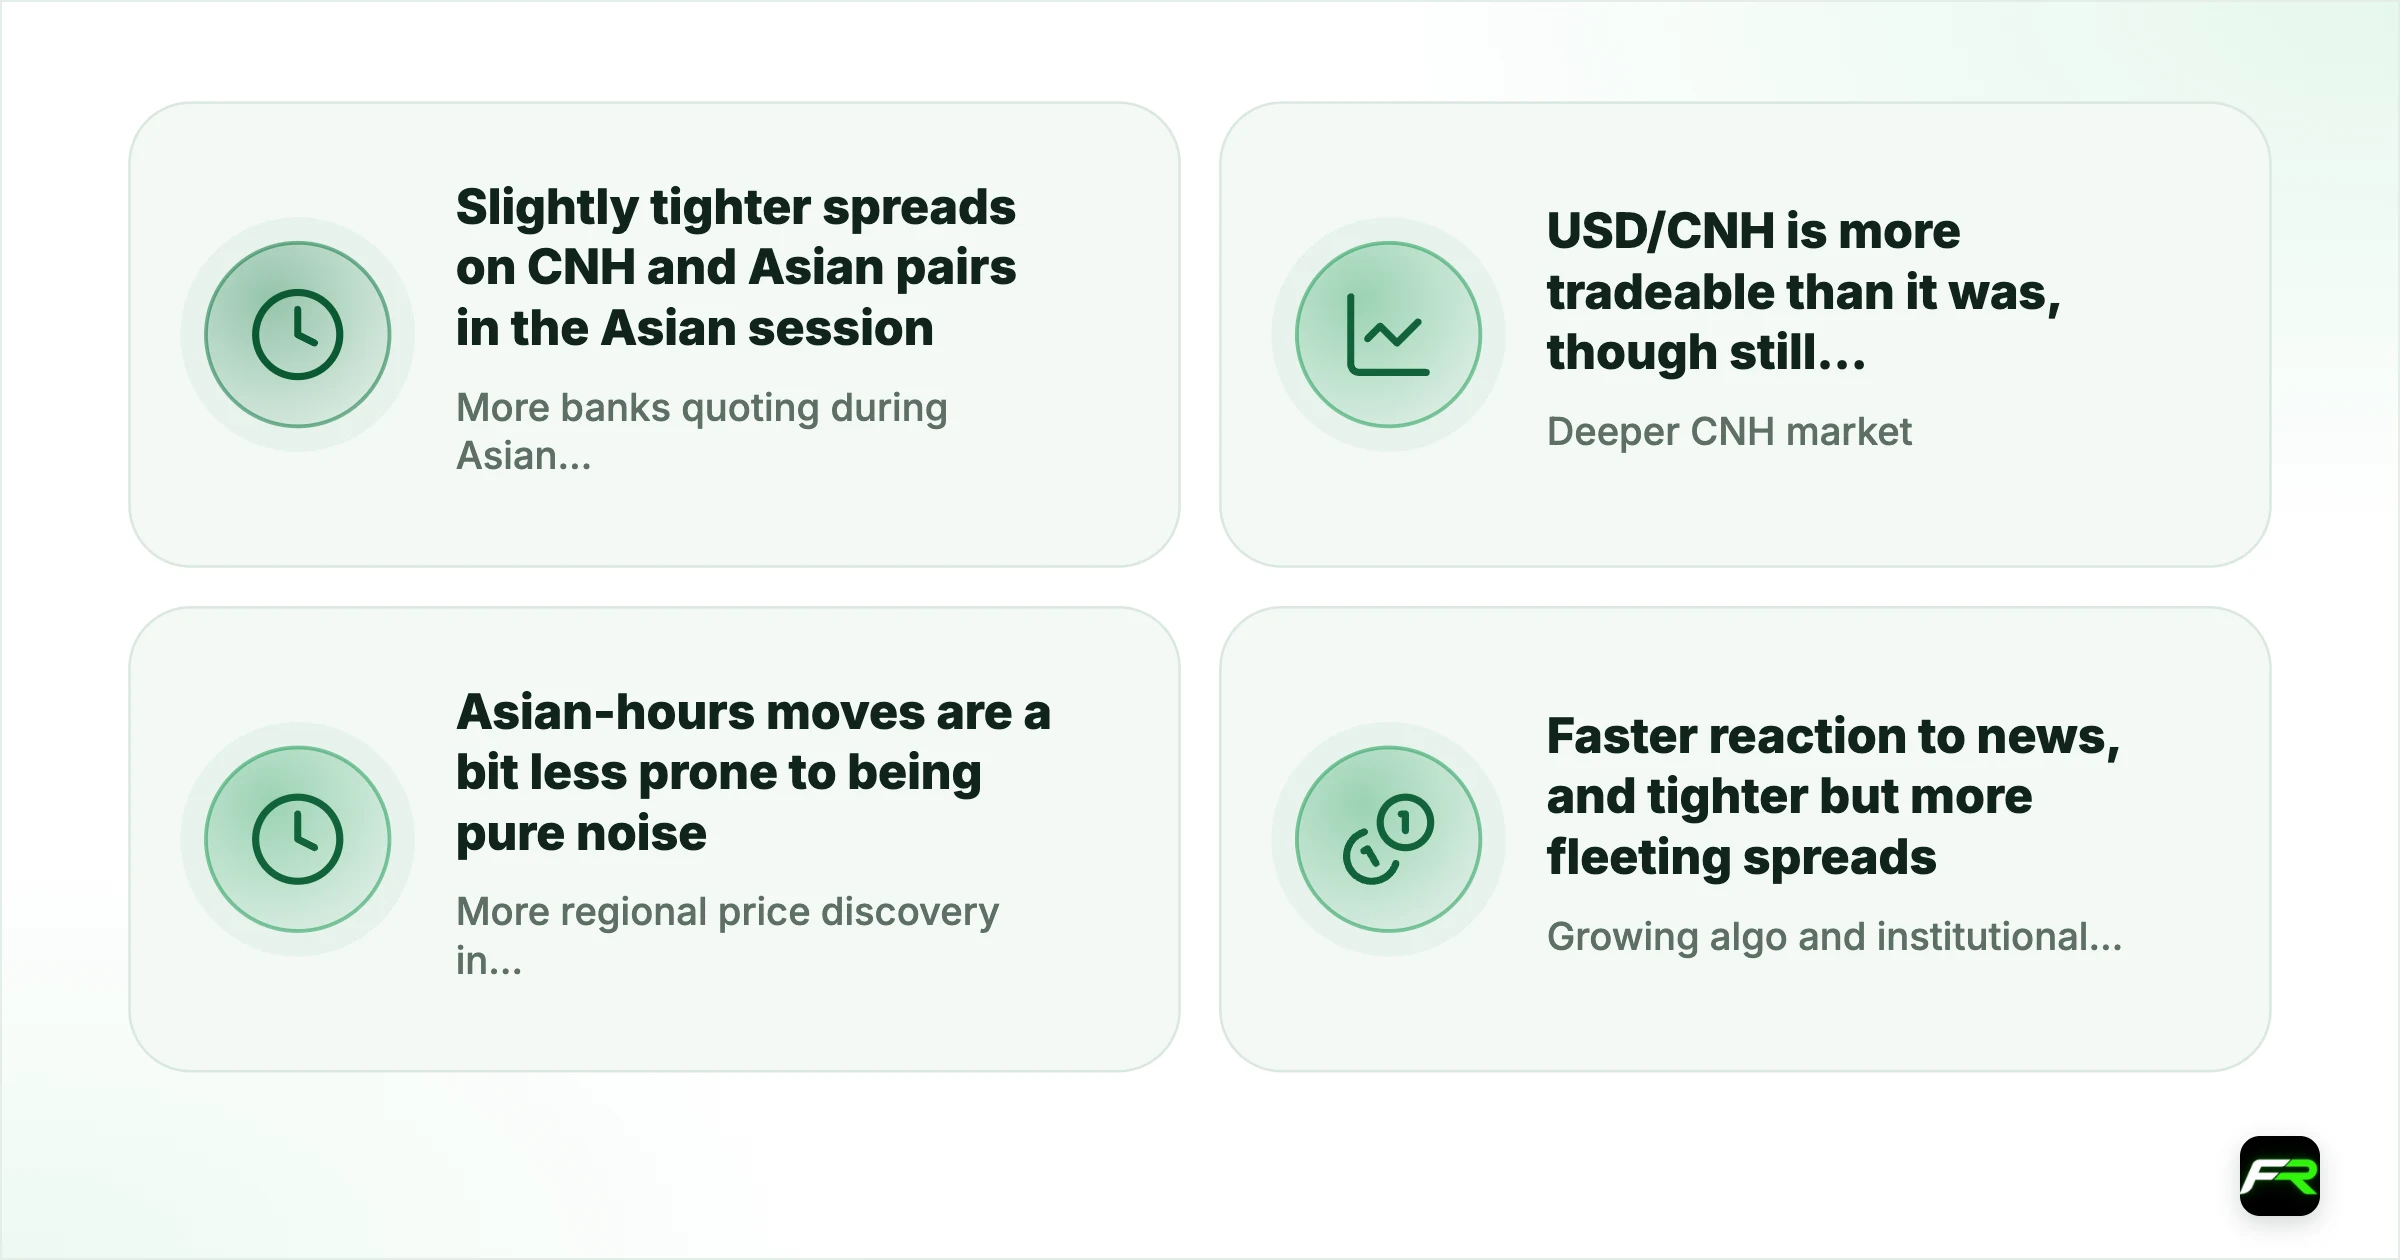
| Effect of deeper Hong Kong liquidity | What you notice |
|---|---|
| More banks quoting during Asian hours | Slightly tighter spreads on CNH and Asian pairs in the Asian session |
| Deeper CNH market | USD/CNH is more tradeable than it was, though still thinner than the majors |
| More regional price discovery in Asia | Asian-hours moves are a bit less prone to being pure noise |
| Growing algo and institutional share | Faster reaction to news, and tighter but more fleeting spreads |
The overall direction is positive for a retail trader: more liquidity in the Asian time zone means better pricing on the pairs that move during your hours, particularly the yuan and other regional currencies. It does not transform the Asian session into the London-NY overlap, but it has narrowed the gap over the years.
The China connection and the risk
Much of Hong Kong’s FX growth is tied to the offshore yuan and to cross-border activity with the mainland. That is also a concentration risk. A significant shift in mainland policy toward the yuan’s offshore use, or a period of stress in the China relationship, would affect Hong Kong’s FX volumes more than it would affect Singapore’s or Tokyo’s. For a trader, the takeaway is that USD/CNH liquidity is better than it used to be but still policy-sensitive, and it can thin quickly around a China event or the Chinese New Year closure.
Wei trades USD/CNH occasionally and noticed the spread had tightened compared with a few years ago, which he attributes partly to the growth of the offshore market centred on Hong Kong. He still treats it as a second-tier pair, wider than the majors and vulnerable to the PBOC fixing, but it is more tradeable than it was, and the deeper Asian-session liquidity generally has meant fewer bad fills on his early-morning entries.
The bigger picture
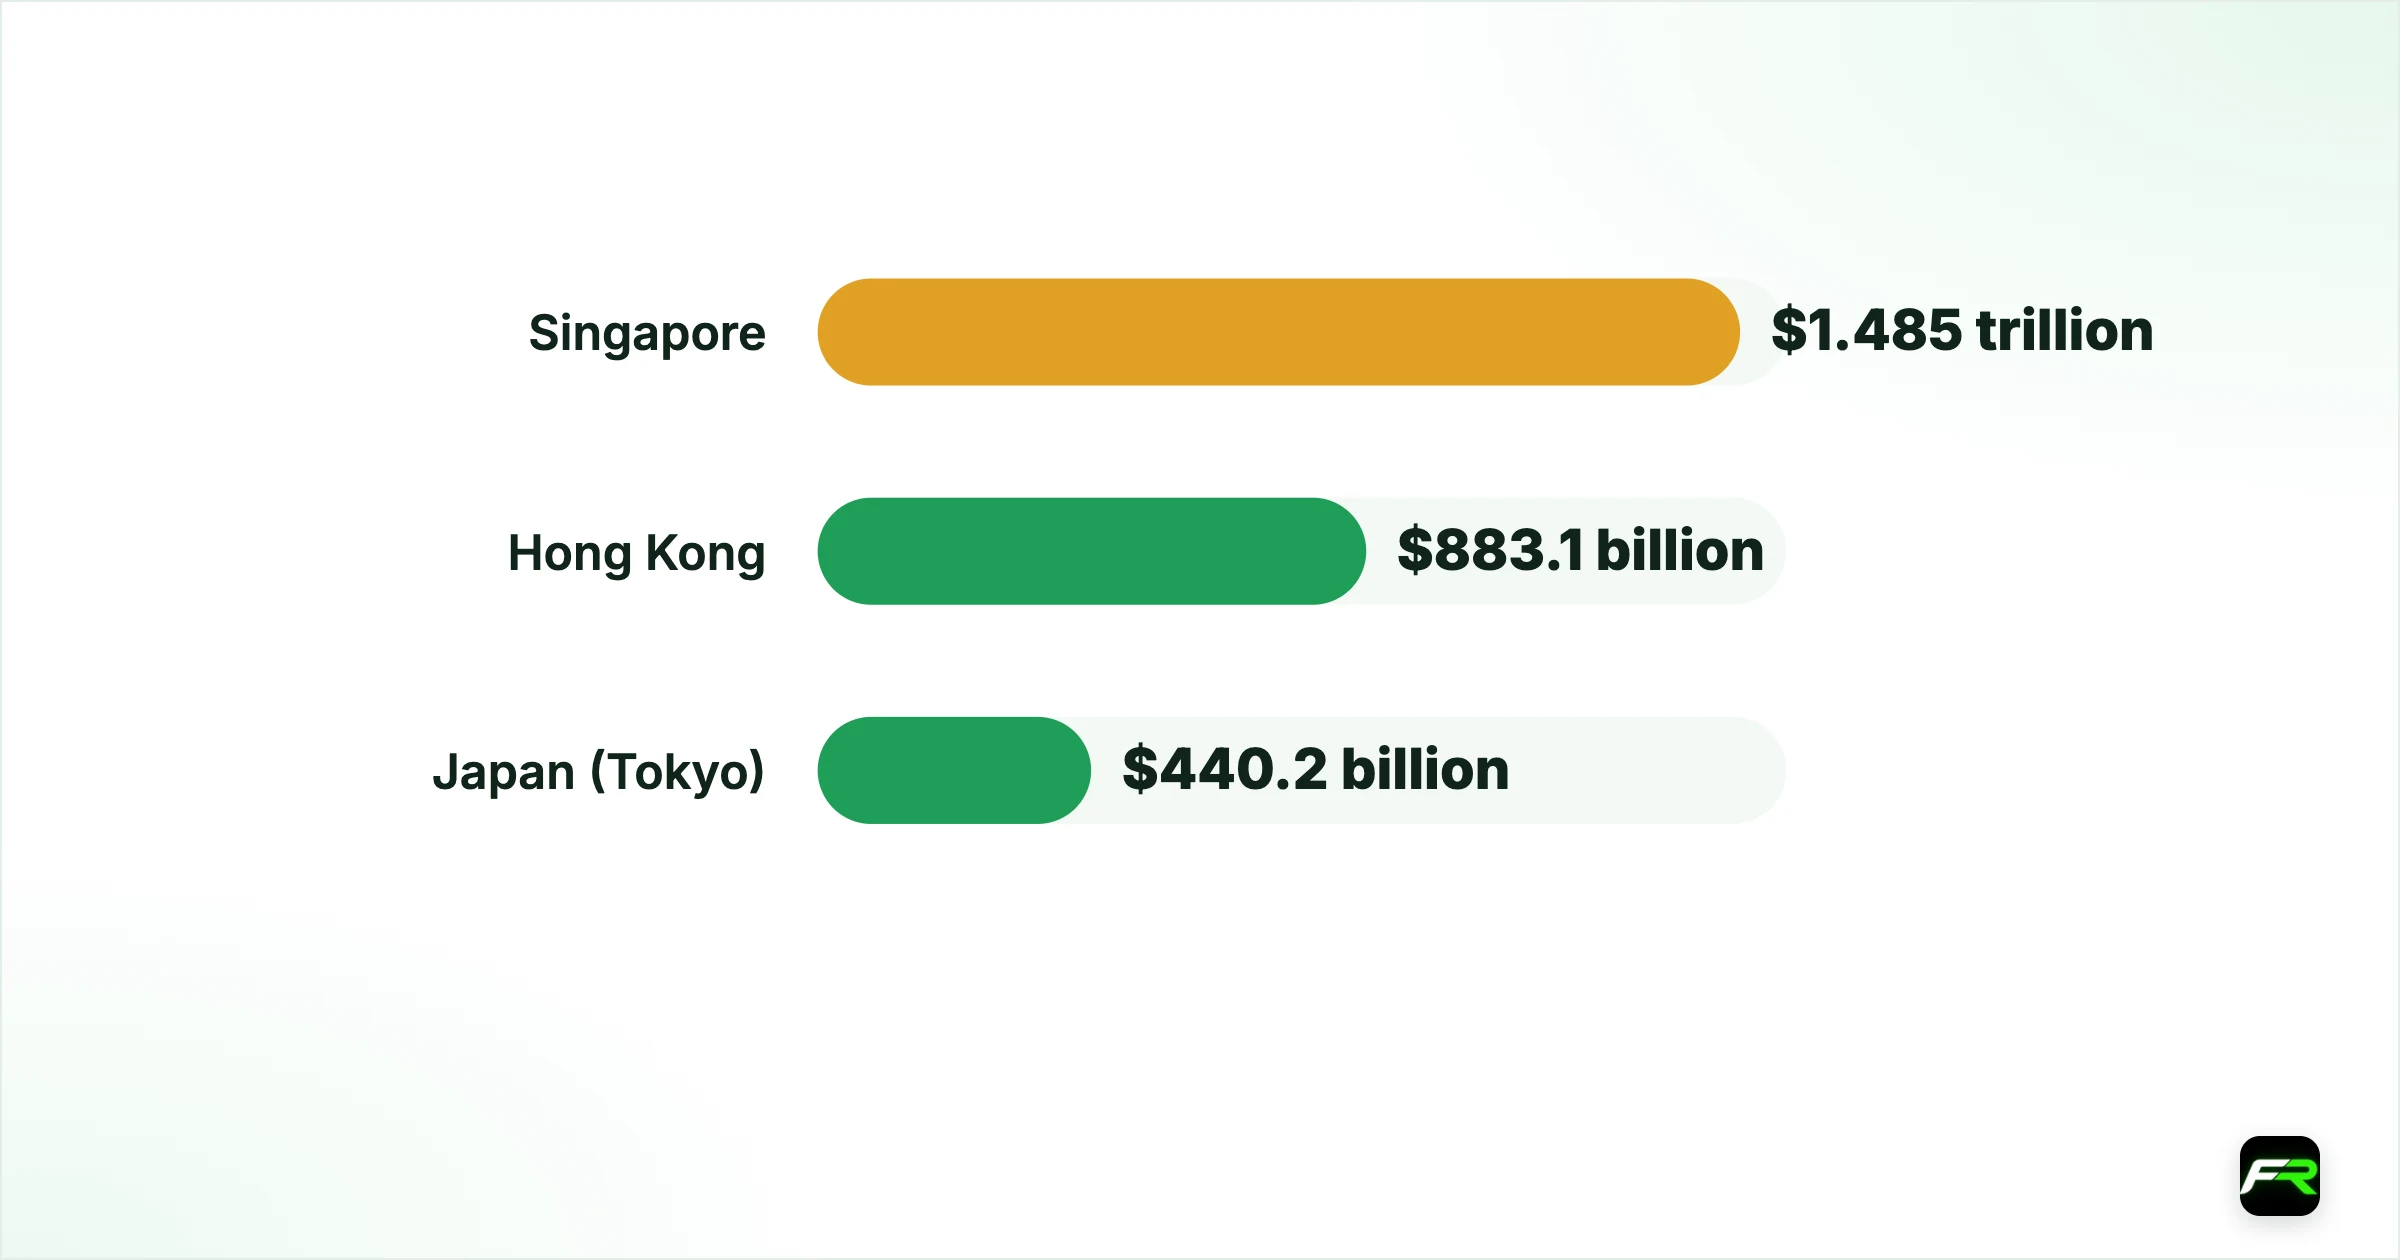
| Centre | Daily FX turnover (April 2025) | Global rank |
|---|---|---|
| Singapore | $1.485 trillion | 3rd |
| Hong Kong | $883.1 billion | 4th |
| Japan (Tokyo) | $440.2 billion | Outside the top 5 |
Figures from the 2025 BIS Triennial Survey, via the Monetary Authority of Singapore, the HKMA and the Bank of Japan's own releases. Singapore is comfortably Asia's largest centre, doing more each day than Hong Kong and Japan combined; Hong Kong is ahead of Tokyo but well behind Singapore. Asian FX centres, Hong Kong, Singapore and Tokyo, have all grown, and a larger share of global forex turnover now happens in the Asian time zone than a decade ago, including more of it during the Tokyo hours covered elsewhere on this site. The global turnover guide puts the worldwide numbers in context.
The Hong Kong Dollar Peg, Explained
Hong Kong runs one of the oldest currency pegs in the world. The Linked Exchange Rate System started on 17 October 1983, and today the Hong Kong dollar trades in a narrow band of HK$7.75 to HK$7.85 per US dollar. The Hong Kong Monetary Authority (HKMA) guarantees both edges.
The guarantees are called convertibility undertakings. At HK$7.85 the HKMA will buy any Hong Kong dollars offered to it, and at HK$7.75 it will sell them. When it buys, the money it takes in shrinks the Aggregate Balance, the cash banks hold at the HKMA. Less cash pushes Hong Kong interbank rates (HIBOR) up, and higher rates pull the currency back from the edge.
The HKMA publishes expected changes in the Aggregate Balance in real time, so the whole market can see the defence happening. That openness is part of why the peg has held through the 1997 Asian crisis, 2008 and every scare since.
What the Peg Means If You Trade USD/HKD
USD/HKD is the most boring pair your broker lists, by design. The whole band is 1,000 pips wide, and the price spends long stretches near one edge or the other. Directional trading is close to pointless. There is no room for a trend.
The action is in the interest rates. When HIBOR is far below US rates, the pair drifts to the weak side at 7.85 and stays there, because holding US dollars pays more. When HIBOR rises above US rates, the pair moves back toward the middle or the strong side. Watching HIBOR tells you more than any chart pattern.
Some retail traders try to collect swap on USD/HKD for that reason. Look at the swap your broker actually pays before trying it. After the broker's markup it is often close to nothing, and the spread can cost more than weeks of swap.
Sources and where to check it yourself
- HKMA: Linked Exchange Rate System: the band, the convertibility undertakings and live Aggregate Balance data
Cite this guide
FX Recap, "Hong Kong’s Forex Volume Hit a Record: Why It Matters to You", updated 30 October 2026, https://fxrecap.com/asia-trading/hong-kong-forex-volume-record
Free to quote with a link. Journalists: data and comment in our press room.
Frequently asked
How big is Hong Kong’s forex market?
$883.1 billion a day in April 2025, per the HKMA's release of the 2025 BIS Triennial Survey, a record for Hong Kong, and the fourth-largest forex centre in the world, though still well behind Singapore's $1.485 trillion.
Why does Hong Kong’s FX volume matter to a retail trader?
Deeper liquidity in the Asian time zone means slightly tighter spreads and more reliable pricing on the pairs that move during Asian hours, particularly the offshore yuan and other regional currencies.
Is USD/CNH still hard to trade?
It is more liquid than it used to be, helped by the growth of the offshore market centred on Hong Kong, but it is still wider than the majors and highly sensitive to the daily PBOC fixing and China policy.
What is the risk in Hong Kong’s FX growth?
It is heavily tied to the offshore yuan and cross-border China activity, so it is more exposed to shifts in Chinese policy and to stress in the China relationship than Singapore’s or Tokyo’s FX volumes.
Is Hong Kong bigger than Singapore for forex trading?
No. Singapore is Asia's largest FX centre and the world's third-largest, at $1.485 trillion a day in the 2025 BIS Triennial Survey, against Hong Kong's $883.1 billion (fourth-largest globally). Singapore alone turns over more than Hong Kong and Japan combined.
Where does the $883 billion figure come from?
The Hong Kong Monetary Authority's own release of the 2025 BIS Triennial Central Bank Survey, covering average daily turnover in April 2025. The BIS runs the survey every three years across dozens of national regulators.
Are Asian trading hours getting better for retail traders?
Slowly, yes. Hong Kong, Singapore and Tokyo have all grown, so a larger share of global forex turnover now happens in the Asian time zone, which improves pricing and depth during those hours.
Related reading
The team behind this guide
Researched, checked and approved by five forex specialists
Every guide is written, fact-checked and edited before it goes live, and updated when the facts change. Spotted an error? Tell us.